
Riza Damanik, Deputy for Entrepreneurship at the Ministry of Cooperatives and SMEs, said on 31 July 2026 that People's Business Credit facilities up to Rp100,000,000 carry no additional collateral of any form, without exception. The basis is Coordinating Minister for Economic Affairs Regulation No. 1 of 2026 on KUR implementation guidelines, in force since 13 January 2026.
For homeowners and business operators in North Bekasi, that sentence settles a worry that surfaces in a lot of living rooms about whether the house certificate has to move into a bank vault. It all turns on one number, and the number is not vague.
Two kinds of collateral, often treated as one
This is where the confusion starts. The KUR guidelines recognise two kinds of collateral, and only one of them disappears on smaller loans.
| Type of collateral | What it looks like | Up to Rp100 million |
|---|---|---|
| Primary collateral | The business or the asset being financed, plus the borrower's capacity to repay | Still applies |
| Additional collateral | Land certificates, vehicle registration books, other personal assets | Cannot be requested |
So the loan is not unsecured. Your business itself is the security, judged on its cash flow. What may not cross the desk is a house certificate, a vehicle book, or any personal asset unconnected to the venture being financed.
The Rp100 million line is not negotiable against a risk profile. The ministry used the phrase "without exception", and it opened complaints through the SP4N-LAPOR channel.
Three tiers, and where the certificate becomes relevant
The 2026 scheme splits KUR into three levels, with a lower rate at the bottom tier.
| Scheme | Facility size | Effective annual rate | Additional collateral |
|---|---|---|---|
| KUR Super Micro | Up to Rp10 million | 3% | No |
| KUR Micro | Above Rp10 million to Rp100 million | 6% | No |
| KUR Small | Above Rp100 million to Rp500 million | 6% | Bank may request |
The dividing line sits exactly at Rp100 million. Below it, certificates never enter the conversation. Above it, a lender may ask for additional collateral. That is the point where an owner should understand what actually happens to the document.
What happens to a certificate above Rp100 million
Pledging a house is not a matter of handing over a folder. The process runs under Law No. 4 of 1996 on Security Interests in Land, and the record stays attached to the certificate until the loan is settled.
- Valuation. The bank appoints a valuer to assess the house or shophouse. The appraised figure almost always lands below market price, and the facility is sized off the appraisal.
- Deed of Granting Security Interest. Signed before a land deed official. The borrower bears the cost, which scales with the loan value, so ask for the breakdown before signing rather than after.
- Registration at the Land Office. The security interest is recorded in the land book and on the certificate. From here, your certificate is formally encumbered.
- The bank holds the document. Ownership stays in your name. What moves is physical custody and the lender's right to execute if the loan sours.
- Roya once it is paid off. The encumbrance does not lift by itself. You have to file for its removal at the Land Office, and we cover the steps and costs in our guide to roya after a mortgage is settled.
Plenty of owners skip that last step. A certificate that is paid off but never released will hold up the next sale or the next pledge.
If the house is still on a mortgage, the certificate is not available
This is what derails working-capital plans most often. While a mortgage runs, the certificate already carries a security interest registered by the mortgage lender, and the document sits with that lender. One asset cannot back two lenders without the first one at the table.
For anyone whose house is less than five years old, that makes a sub-Rp100 million requirement the more realistic route, since it never touches the certificate. Larger needs are usually served through the existing lender rather than a new one.
No payslip, no problem: the business is what gets assessed
Because KUR's primary collateral is the venture being financed, the bank's attention shifts from employment paperwork to operating evidence: business account statements, sales records, and basic legality such as a business identification number. Mortgage applications work differently and still weigh personal income, which we compare in our guide to mortgages for small-business owners and freelancers without payslips.
One more 2026 change is worth noting for anyone who has already used KUR before. Operators in the production sector and in export-oriented trade no longer face a cap on how many times they may access the scheme. The next facility is judged on merit rather than on a tally.
What this means for shophouse owners on Jl. Raya Perjuangan
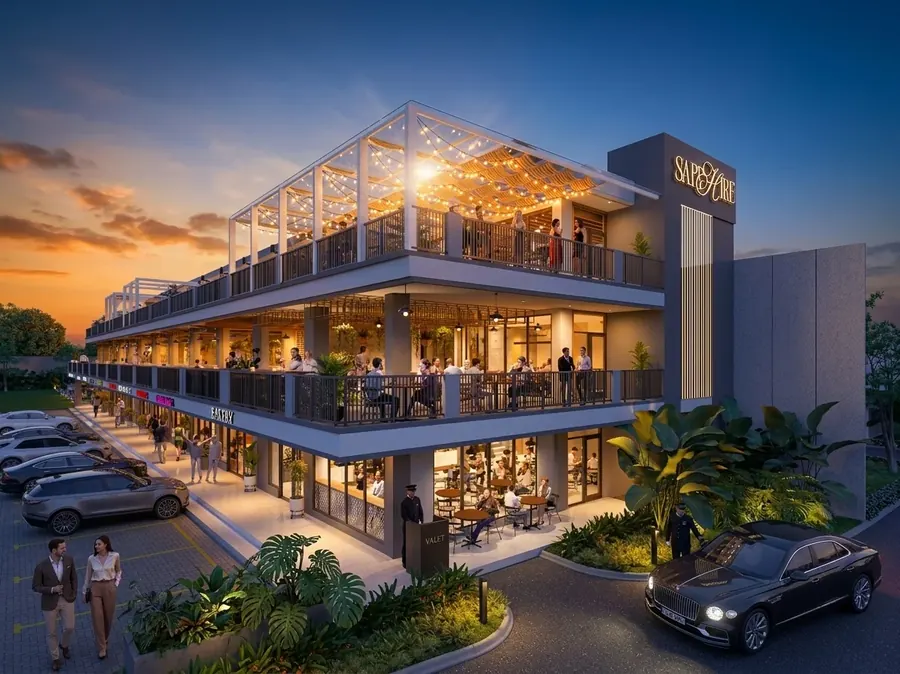
A three-storey unit like Sapphire usually gets bought out of two separate pockets: one for the property, one for the working capital that brings it to life. The second pocket is the one people force down the wrong path, because they assume business funding and property purchase have to run through the same door.
For fit-out, equipment, or opening stock, the figure often lands under Rp100 million. In that range the shophouse certificate stays with you, and what the bank weighs is the business plan. To gauge what a sensible working-capital figure looks like for the North Bekasi corridor, we sized the local market in our piece on the food-and-beverage SME wave in North Bekasi.
One legal detail gets left behind a lot: the title type on a unit determines whether it can be pledged at all, and for how long. The practical difference is set out in our comparison of freehold and building-right titles.
Want to know where your unit's certificate stands?
The Kingspoint team can walk you through the title status and documents for the Sapphire shophouse and the Emerald 70 house in North Bekasi, so your working-capital plan is built on the real position from the start.
Chat on WhatsApp