
Through 2026, Indonesia's tax office (DJP) has been matching property-sector data ever more closely — bank mortgage records, rental account flows, right down to the books of companies that lease offices and ruko. For a ruko owner, one obligation often slips off the radar: the tax on rental income. The moment a ruko is rented out, especially to a company, a Final Income Tax under Article 4 paragraph (2) attaches to every rupiah of rent that comes in.
The rate is 10% of the gross value. It rests on Government Regulation No. 34 of 2017 on income tax from the leasing of land and/or buildings. Being final means that once it's deposited for that rental income, the tax on it is considered settled and isn't recalculated as the same object in the Annual Tax Return. What trips up many ruko owners isn't the 10% figure, but who is obliged to withhold and deposit it. The answer differs depending on whether the tenant is a business entity or an individual.
What Counts as the "Gross Value"
Before we get to who withholds, one term needs clearing up: gross value. Many assume the 10% is charged only on the base rent. But if the rental agreement includes extra components such as maintenance, security, cleaning, or a service charge, those get folded into the gross, as long as they sit in the same rental contract package.
A simple example: the ruko rent is set at Rp120 million a year, plus a Rp12 million service charge. The tax base becomes Rp132 million, not Rp120 million, and 10% of that is Rp13.2 million. So it pays to separate what is genuinely rent from what is a pure reimbursement inside the agreement — because that's what sets the tax figure. The numbers here are illustrative; the exact math depends on the contract.
Company vs Individual Tenant: Who Withholds, Who Deposits
Now, here's the part most people get backwards. If the tenant is a business entity — a PT, CV, foundation, or agency that qualifies as a withholding party — they are the ones obliged to withhold 10% from the rent, deposit it to the state, then issue a withholding slip to the owner. So the ruko owner receives rent that's already been cut, meaning net 90%.
The other way around, if the tenant is an ordinary individual who isn't a withholding party, the responsibility shifts to the owner. The owner has to deposit that 10% themselves and report it. Here's the short version.
| Obligation | Company tenant (PT/entity) | Individual tenant |
|---|---|---|
| Withhold 10% of rent | Tenant (company) | Not withheld by tenant |
| Deposit to the state | Tenant (company) | Ruko owner |
| Issue the withholding slip | Tenant issues, owner keeps | Owner keeps own deposit proof |
| File the periodic return | Tenant (company) | Ruko owner |
| What the owner receives | Net, already cut to 90% | Gross, but must self-deposit |
If the tenant is a company
A company renting the ruko will withhold 10% when it pays the rent, deposit it, then issue an Article 4(2) withholding slip. Since DJP rolled out its Coretax system, this slip is issued through that platform. As the owner, ask for that slip and file it carefully — it's valid proof your rental tax has been paid. Because it's final, the owner doesn't need to deposit anything further on that rental income. How to read and store the slip in the new system is something we cover separately in our Coretax DJP 2026 guide to reporting rental income tax.
If the tenant is an individual
Here the owner is both depositor and filer. The flow: create a billing code for the Article 4(2) Final Tax, deposit it no later than the 10th of the following month after the rent is received, then report it via the periodic return no later than the 20th of the following month. Late deposit or filing can draw interest penalties. This self-deposit mechanism for owners leasing to individuals is exactly the same one that applies to homes, which we've laid out in our guide to the 10% Final Tax on house rent for owners.
Note: this piece is analytical and educational, not tax advice for a specific case. Rates, deadlines, and reporting procedures can change, and how they apply depends on the tenant's status and the terms of the rental agreement. To confirm your ruko's obligations — including whether the tenant qualifies as a withholding party — check the latest rules on the official DJP site or consult a tax adviser. All figures here are illustrative.
Property Tax Oversight Is Tightening in 2026
Worth noting, DJP no longer waits for voluntary reporting. With banking data and third-party reporting increasingly integrated, undeclared rental income is easier to spot — especially when the tenant is a company that records that rent expense in its own books. So for a ruko owner, logging the rent and keeping the withholding slip isn't mere paperwork, it's a safety net if an audit ever comes.
That's why, before signing a contract, it helps to settle things upfront: is the tenant an entity or an individual, who bears the withholding, and how the slip gets handed over. A tidy agreement at the start avoids the "why is the rent that came in short?" confusion later.
Tying It Back to Ruko Sapphire Investors
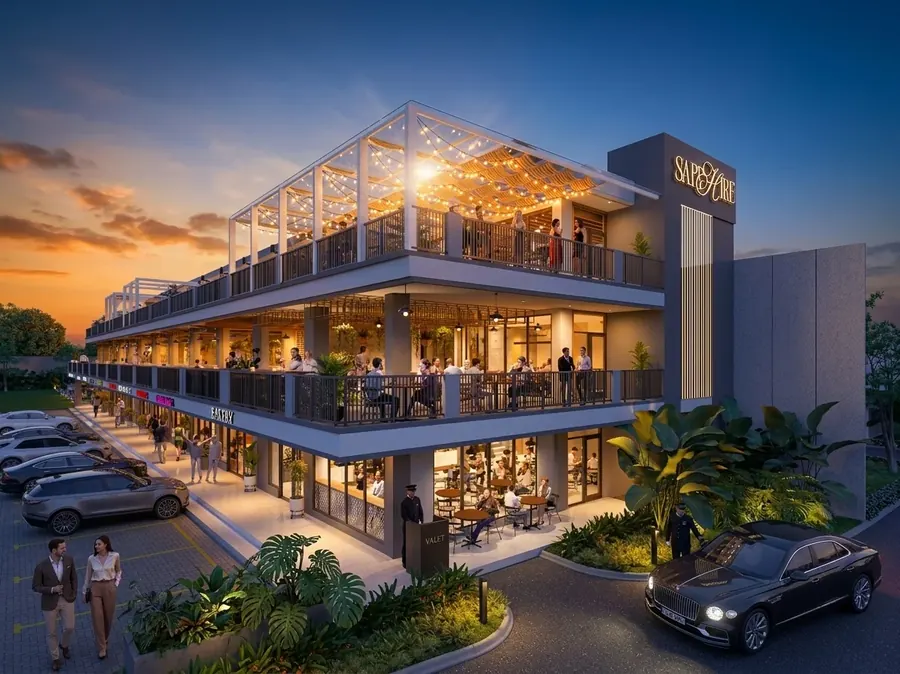
For anyone weighing a ruko as a rental asset, this tax math is part of the yield picture. Take Ruko Sapphire at Kingspoint Residence, Jl. Raya Perjuangan, North Bekasi, by Mandiri Development. Each unit is three storeys plus a rooftop, land area 72 m² with 172 m² of building, 2,200 VA of power, in the Rp1.9 billion range. It sits 5 minutes from Stasiun Bekasi and Summarecon Mall Bekasi, a fit for a small office or an F&B outlet.
If a unit like this is rented to a company, that tenant is the one who withholds and deposits the 10% Final Tax, and the owner receives net rent plus a slip. If it's rented to an individual trader, it's the owner's turn to self-deposit. Both are valid; they just differ in who holds the administrative duty. On the potential rental demand from small businesses and F&B in this area, we go deeper in our piece on the UMKM and F&B momentum for Ruko Sapphire in the second half of 2026.
The point is, ruko rent is tempting, but there's a 10% that was never the owner's to begin with. Knowing who has to withhold and deposit it before the contract is signed keeps the rental cash flow honest, and dealings with the tax office far calmer.
Want details on investing in & renting out Ruko Sapphire?
The Kingspoint team can walk you through the specs, pricing, and rental-potential picture for the Ruko Sapphire unit in North Bekasi, so you have clear numbers before deciding as an investor.
Chat on WhatsApp Now